By Charles West October 6, 2026
The current Visa VAMP thresholds combine qualifying card-not-present fraud and disputes against settled Visa transactions. In the U.S., Canada, Europe and Asia Pacific, the Excessive Merchant threshold is 150 basis points from April 1, 2026, subject to Visa’s applicable count conditions. Merchants approaching that level should verify network data, stop new disputes and fraud, control enumeration, and involve their acquirer early.
The biggest VAMP mistake is treating it like an ordinary chargeback percentage. It is not. The Visa Acquirer Monitoring Program uses Visa network data, includes both qualifying fraud and disputes, applies minimum-count conditions, and separately monitors enumeration activity such as large-scale card testing.
That distinction matters before a merchant receives a formal risk notice. A generic dashboard may show an apparently comfortable chargeback ratio while the Visa-specific calculation is moving in a different direction because of fraud reports, dispute timing, pre-dispute resolution or the transaction population Visa uses as its denominator.
Visa also evaluates acquiring institutions, not only individual merchants. Your acquiring bank or payment facilitator therefore has its own reason to intervene before excessive performance becomes persistent.
Visa VAMP Thresholds at a Glance
The Visa VAMP thresholds changed after the program’s original rollout, which is why merchants should be skeptical of tables copied from older 2025 articles.
Visa’s official VAMP fact sheet originally listed a 220-basis-point Excessive Merchant threshold for Asia Pacific, Canada, Europe and the United States. The same Visa source expressly states that the threshold decreased to 150 basis points effective April 1, 2026.
| Metric | Current Published Threshold | Minimum Condition | Applies To | Practical Meaning |
| Acquirer Above Standard | ≥50 bps | ≥1,500 fraud + disputes monthly in AP, Canada, EU and U.S.; different CEMEA condition | Acquirer portfolio | Portfolio has reached Visa’s Above Standard level |
| Acquirer Excessive | ≥70 bps | Same applicable regional minimum | Acquirer portfolio | Higher portfolio-level VAMP identification |
| Excessive Merchant — AP, Canada, EU, U.S. | ≥150 bps | ≥1,500 monthly fraud + disputes | Merchant where applicable under the VAMP framework | Current merchant threshold effective April 1, 2026 |
| Excessive Merchant — LAC | ≥150 bps | ≥1,500 monthly fraud + disputes | Merchant | Published LAC merchant test |
| Excessive Merchant — CEMEA | ≥220 bps | ≥150 fraud + disputes and amount ≥USD 75,000 | Merchant | Region-specific merchant test |
| Enumeration ratio | ≥2,000 bps | Ratio test | Enumeration monitoring | At least 20% of authorization attempts identified as enumerated |
| Enumeration count | ≥300,000 | Count test | Enumeration monitoring | Very high volume of identified enumerated authorization attempts |
Verified against current Visa program materials as of October 2026.
A basis point is one-hundredth of one percentage point:
- 50 bps = 0.50%
- 70 bps = 0.70%
- 100 bps = 1.00%
- 150 bps = 1.50%
- 2,000 bps = 20.00%
The count requirement can be just as important as the percentage. A low-volume merchant can have a relatively high estimated Visa dispute ratio without satisfying the published merchant-level count condition, while a large merchant may cross both tests quickly.
Visa’s public fact sheet also states that the standalone Excessive Merchant criteria apply when the acquirer is not itself identified as Above Standard or Excessive under the framework. VAMP therefore operates partly as merchant risk monitoring and partly as acquirer portfolio oversight.
For the authoritative threshold source, use Visa’s Visa Acquirer Monitoring Program fact sheet.
How the VAMP Ratio Calculation Actually Works
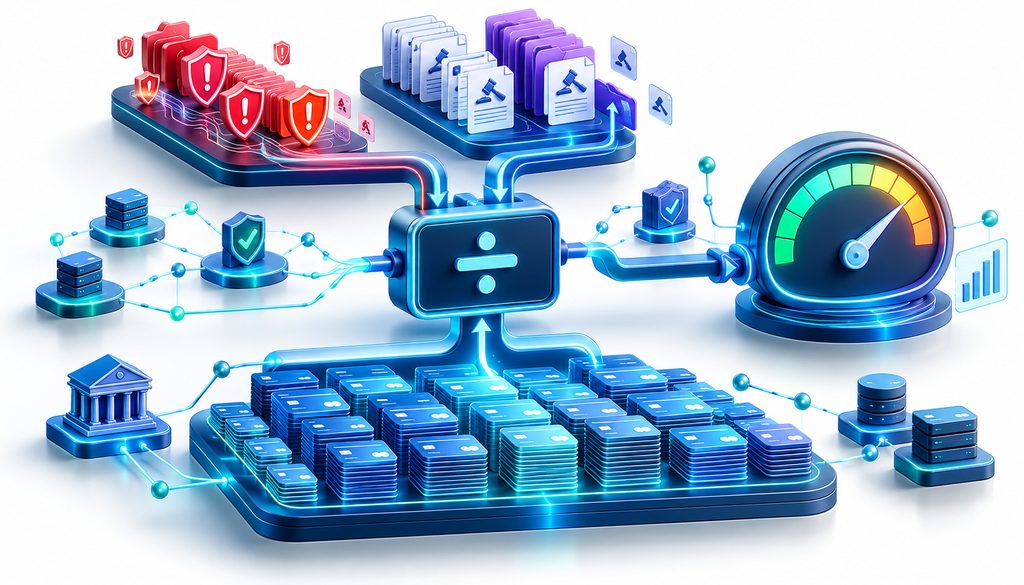
The official VAMP ratio calculation is fundamentally a count-based equation:
VAMP ratio = qualifying fraud (TC40) + qualifying disputes (TC15) ÷ settled Visa transactions (TC05)
TC40 records represent Visa fraud reporting. TC15 represents dispute activity. TC05 provides the settled transaction population used in the denominator. The core VAMP metric applies to card-not-present VisaNet transactions covered by the program.
That does not mean the merchant should export “fraud” and “chargebacks” from a gateway, add the columns together and assume the answer matches Visa.
Visa’s official materials say the VAMP calculation excludes disputes resolved through qualifying pre-dispute solutions, subject to the timing of Visa’s data extract. It also excludes qualifying TC40 fraud associated with Compelling Evidence 3.0, again subject to extract timing.
Visa’s treatment of qualifying fraud also makes Compelling Evidence 3.0 transaction-history requirements relevant when first-party misuse is contributing to the fraud count. CE 3.0 does not automatically remove every fraud report; Visa’s eligibility and data-extract timing still control the VAMP treatment.
Worked VAMP Ratio Example
Real-World Example — hypothetical data
Assume a U.S. ecommerce merchant records the following Visa activity during one monitoring month:
- 120,000 settled Visa transactions
- 1,050 qualifying fraud records
- 780 qualifying disputes
First calculate the numerator:
1,050 + 780 = 1,830
Then divide by settled transactions:
1,830 ÷ 120,000 = 0.01525
Expressed as a percentage:
1.525%
Expressed in basis points:
152.5 bps
This hypothetical merchant is above the current 150-bps VAMP merchant threshold for the United States and also exceeds the published 1,500-record monthly count condition.
Now consider a much smaller merchant with 5,000 settled transactions and 80 qualifying fraud and dispute records.
Its estimated percentage would be:
80 ÷ 5,000 = 1.60%, or 160 bps
The percentage is higher, but the 80-record numerator is far below the published 1,500-count condition for the U.S. merchant-level test. This is why a percentage viewed in isolation can be misleading.
Merchants should also avoid assuming a TC40 fraud record and a TC15 dispute involving the same underlying purchase will always be treated exactly as their internal dashboard does.
Visa’s public fact sheet provides the formula but does not publicly document every possible deduplication scenario. Ask your acquirer for the actual Visa numerator if your own calculation differs materially.
VAMP Replaced VDMP and VFMP: What Actually Changed?
The Visa Acquirer Monitoring Program represents a broader change than simply renaming Visa’s old chargeback programs.
Visa states that the evolved program consolidated five existing fraud and dispute monitoring programs into a single acquirer program and reduced 38 separate remediation processes into a more consolidated framework. Visa also shifted toward lifecycle risk management and incorporated enumeration criteria.
| Earlier Monitoring Model | VAMP Model |
| Multiple fraud and dispute monitoring programs | Broader consolidated acquirer monitoring framework |
| Visa Dispute Monitoring Program focused on excessive disputes | Fraud and disputes contribute to one central VAMP ratio |
| Visa Fraud Monitoring Program addressed fraud separately | Qualifying fraud is incorporated into the combined metric |
| Traditional emphasis on merchants exceeding isolated metrics | Acquirer portfolio performance is also monitored |
| Card testing handled outside the core dispute ratio | Explicit enumeration ratio and count criteria |
| Multiple remediation workflows | More consolidated remediation approach |
The change means merchants should stop asking only, “What is my chargeback percentage?”
A better monthly risk review asks:
- What is my estimated Visa VAMP ratio?
- How much of the numerator is fraud?
- How much is non-fraud dispute activity?
- What is happening to the settled transaction denominator?
- Is card testing contributing to enumeration concerns?
- Are eligible disputes being intercepted before formal dispute creation?
Those questions produce a more useful picture of merchant risk monitoring than a single chargeback number.
What Visa Enumeration Monitoring Measures
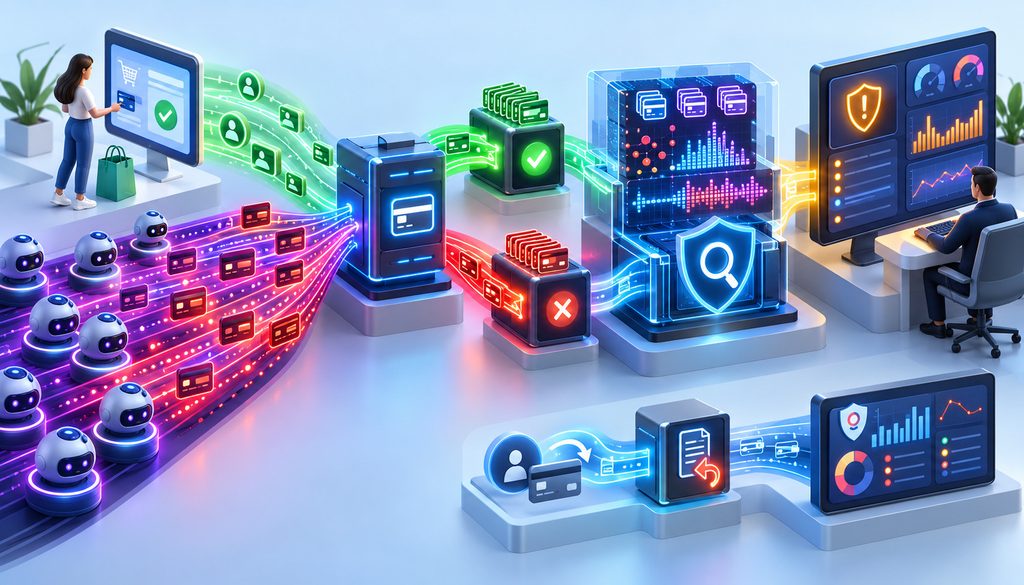
Enumeration is essentially card testing at scale. Attackers submit large numbers of authorization attempts to discover usable payment credentials or determine which combinations of card data are valid.
Visa measures enumeration separately from the core VAMP fraud-and-dispute ratio.
The published formula is:
Enumeration ratio = identified enumerated authorization attempts ÷ total authorization attempts
Visa’s official VAMP material specifies both approved and declined authorization attempts when defining these populations. Its published enumeration thresholds are 2,000 basis points, or 20%, and at least 300,000 enumerated authorization attempts.
This distinction matters because a merchant can have acceptable Visa VAMP thresholds performance for fraud and disputes yet still be experiencing an aggressive enumeration attack.
Possible operational warning signs include:
- sudden bursts of low-value payment attempts;
- unusually high decline volumes;
- repeated authorization attempts within seconds;
- large increases in checkout traffic without matching sales;
- automated behavior across many accounts or cards;
- unusual BIN or account-number testing patterns.
These are practical warning signs, not Visa’s proprietary enumeration-detection algorithm.
For ecommerce merchants, controls such as EMV 3DS 2.2 and network tokenization can form part of a broader card-not-present fraud strategy, alongside velocity controls, device intelligence and bot mitigation.
What Happens After Your MID Crosses a VAMP Threshold?
Crossing a threshold does not mean Visa directly reaches into a merchant account and terminates the MID. Visa sets network requirements; the merchant’s day-to-day relationship normally runs through an acquiring bank, payment facilitator or another contracted provider.
A typical sequence looks like this:
- Visa identifies qualifying performance: Monthly network monitoring evaluates applicable VAMP fraud, dispute and enumeration data.
- The acquirer receives program information: The issue may involve the portfolio, a merchant, enumeration activity or more than one category.
- The merchant-facing risk team becomes involved: Depending on the processing structure, that may be the acquiring bank, payment facilitator or merchant-services provider.
- The root cause is investigated: Fraud, card testing, fulfillment failures, refunds, subscription problems and customer-service failures should be analyzed separately.
- Chargeback monitoring program remediation begins: Controls are changed and performance is measured during subsequent reporting periods.
- Persistent excessive activity can produce commercial consequences: The acquirer may tighten processing controls, change reserve requirements, require additional fraud tools or reconsider the merchant relationship.
- Exit occurs under the applicable VAMP process: Visa’s public Core Rules refer detailed VAMP identification and exit requirements to the current VAMP Guide rather than publishing one universal merchant exit timetable.
The distinction among participants matters. Visa, the acquiring bank, processor, payment facilitator, ISO and gateway do not perform the same function.
VAMP Fines and Assessments: What Merchants Actually Pay
Search results for excessive chargeback program fines often make the economics look simpler than they are.
A merchant can face at least three different categories of cost:
| Cost | Who Creates It? | What the Merchant Should Verify |
| Network VAMP assessment | Visa under applicable network/program rules | Program status, month, classification and current assessment terms |
| Contractual monitoring/pass-through fee | Acquirer or payment provider under merchant agreement | Contract clause and calculation |
| Ordinary dispute/chargeback fee | Merchant provider | Per-dispute pricing in merchant agreement |
A network assessment against an acquirer is not automatically identical to a merchant fee.
Visa’s public VAMP fact sheet provides the performance thresholds, formulas, count requirements and advisory-period history, but it does not provide a complete current public merchant-facing dollar schedule for every VAMP scenario. Visa’s April 2026 Core Rules also refer several detailed VAMP mechanics to the program guide.
That is why unsupported online “fine schedules” should not be copied into a merchant notice response.
A merchant may separately experience:
- ordinary chargeback fees;
- reserve increases;
- rolling-reserve requirements;
- delayed funding;
- additional monitoring;
- fraud-control requirements;
- processing restrictions;
- account termination.
Those consequences arise from the merchant’s acquiring relationship and risk profile, not automatically from a universal Visa merchant fee table.
The original VAMP advisory period ended September 30, 2025. A merchant receiving a notice in 2026 should therefore not assume the initial rollout grace period still applies.
For network rules beyond the fact sheet, consult the current Visa Core Rules and Visa Product and Service Rules.
Mastercard ECP Thresholds vs Visa VAMP Thresholds
Mastercard ECP thresholds should be managed separately from Visa’s framework.
Mastercard’s 2026 Security Rules and Procedures — Merchant Edition confirms that the Excessive Chargeback Program remains active and includes Excessive Chargeback Merchant and High Excessive Chargeback Merchant classifications.
The current public merchant manual directs readers to Mastercard’s Data Integrity Monitoring Program documentation for detailed ECP threshold information rather than reproducing all numerical criteria in that manual.
| Feature | Visa VAMP | Mastercard ECP |
| Main metric | Qualifying fraud + disputes relative to settled Visa transactions | Mastercard chargeback performance under ECP methodology |
| Fraud in primary metric? | Yes | ECP itself is a chargeback-monitoring program |
| Disputes/chargebacks? | Yes | Yes |
| Merchant count conditions | Yes, region-specific conditions apply | Governed by current Mastercard ECP/Data Integrity criteria |
| Portfolio monitoring | Strong acquirer-level component | Acquirer has merchant-monitoring responsibilities |
| Enumeration metric | Yes, separately measured | Not the defining ECP measurement |
| Merchant classifications | VAMP merchant/acquirer criteria | ECM and HECM |
| Network | Visa transactions only | Mastercard transactions only |
Mastercard states that ECP is designed to ensure each acquirer continuously monitors merchant-level chargeback performance and allows Mastercard to identify when monthly ECP thresholds have been exceeded.
For the latest authoritative documentation, see Mastercard’s rules and compliance resources.
Do not combine Visa and Mastercard transactions into one homemade “network chargeback ratio.” A merchant may be healthy under the Visa VAMP thresholds while triggering Mastercard monitoring, or the reverse.
A Month-by-Month Chargeback Monitoring Program Remediation Plan
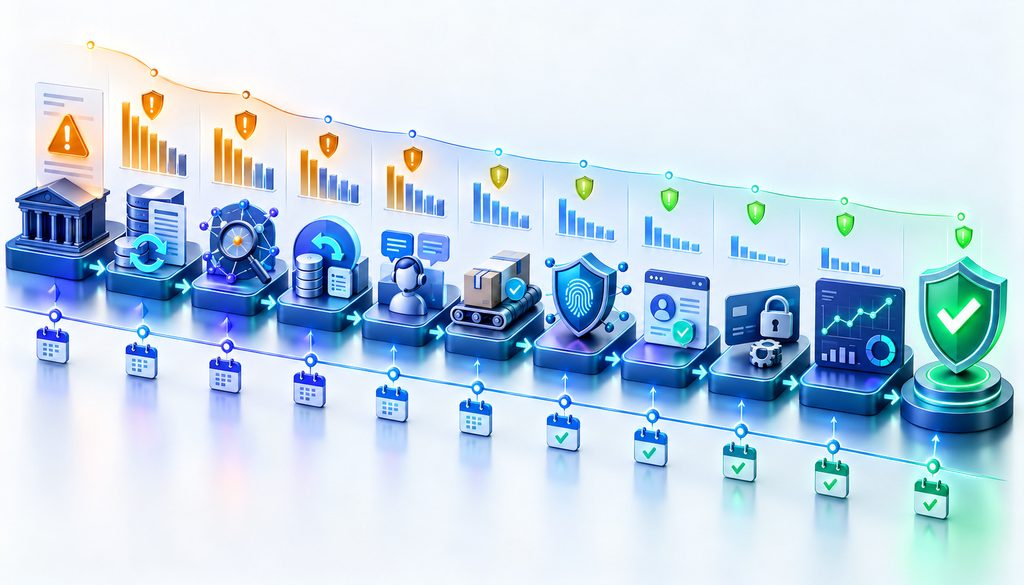
Successful chargeback monitoring program remediation starts with knowing what actually drove the network result.
First 72 Hours: Establish the Real Numbers
Before changing fraud settings, obtain the data.
Confirm:
- affected MID;
- exact reporting month;
- official VAMP numerator;
- settled Visa transaction denominator;
- qualifying fraud count;
- qualifying dispute count;
- whether merchant or portfolio identification applies;
- enumeration findings;
- top dispute categories;
- major fraud sources;
- refund delays;
- gateway-versus-network reporting differences.
A concise request to the acquirer’s risk team can say:
Please provide the affected MID, Visa reporting month, VAMP classification, network numerator and denominator, fraud/dispute split, any enumeration findings, and the remediation milestones your team expects us to meet. We are reconciling Visa data against our gateway, order, refund and dispute records and will provide our corrective-action plan.
This approach is far more useful than asking, “Why is my chargeback ratio so high?”
Month 1: Stop New Fraud and Disputes
The fastest improvement comes from preventing new cases from entering the pipeline.
Review refund speed, cancellation handling, billing descriptors, customer-service response, delivery delays and product expectations. Those operational failures frequently create avoidable disputes even when the transaction itself was legitimate.
Fraud controls should be examined separately. Review:
- AVS and CVV where appropriate;
- 3-D Secure;
- device risk;
- velocity controls;
- IP and account patterns;
- bot mitigation;
- suspicious promotional campaigns;
- unusually risky products or fulfillment routes.
When apparently legitimate orders later produce fraud claims or chargebacks, triangulation fraud and reshipping scams are among the patterns worth testing for during root-cause analysis.
Do not respond to a VAMP notice by simply turning every fraud rule to maximum sensitivity. That can create false declines while leaving the actual fraud source untouched.
Month 2: Add Pre-Dispute Intervention
The VAMP ratio calculation can benefit when qualifying disputes are resolved through eligible pre-dispute mechanisms before the applicable Visa data extract.
Operational tools can include:
- Visa Rapid Dispute Resolution (RDR);
- Visa Order Insight;
- other eligible pre-dispute workflows available through the merchant’s provider;
- fast customer-service resolution;
- refund-before-dispute procedures where justified.
RDR is not a magic VAMP switch. Eligibility varies, and data-extract timing matters.
The same principle applies to friendly-fraud evidence. If a formal dispute has already occurred, merchants need structured documentation rather than a generic receipt.
Once a dispute has entered formal representment, the merchant’s focus shifts from prevention to assembling a concise chargeback rebuttal letter and supporting evidence that directly addresses the dispute reason.
Month 3: Prove the Trend Is Sustainable
By Month 3, the risk team should be able to see more than promises.
Track Visa-specific metrics weekly:
| KPI | Week 1 | Week 4 | Goal |
| Settled Visa transactions | 28,000 | 30,500 | Context |
| Qualifying fraud | 270 | 205 | Down |
| Qualifying disputes | 165 | 130 | Down |
| Estimated VAMP ratio | 155 bps | 110 bps | Down |
| Pre-dispute interventions | 38 | 76 | Monitor |
| Completed refunds | 410 | 455 | Timely |
| Authorization attempts | 36,000 | 38,200 | Context |
| Enumeration indicators | Elevated | Low | Down |
These figures are hypothetical. The important part is the structure.
Break results down by product, marketing campaign, transaction channel, subscription cohort, fulfillment method and fraud source. A VAMP problem caused by one high-risk affiliate campaign requires a different fix from excessive disputes caused by delayed shipping.
Risk-team perspective: A merchant that can identify the root cause, document corrective controls and show week-over-week improvement is easier for an acquiring bank to support than one that argues only about the headline percentage.
Months 4+: Exit and Prevent Recurrence
Continue monitoring after the ratio declines.
Visa’s public Core Rules state that VAMP exit is handled as specified in the applicable VAMP Guide. The publicly accessible rulebook does not provide one universal consecutive-month exit requirement that should be quoted for every merchant, region and identification type.
Ask the acquirer to document:
- the performance target;
- required monitoring period;
- any additional controls;
- reporting cadence;
- reserve implications;
- formal exit confirmation.
Do not dismantle fraud or customer-service controls after one strong month.
When Will an Acquirer Help You — and When Will It Terminate You?
Exceeding Visa VAMP thresholds does not create the same outcome at every acquiring bank.
A merchant with a clear root cause, cooperative management and measurable improvement may be supportable. A merchant with growing losses, uncontrolled card testing, misleading underwriting information or repeated monitoring problems may fall outside the acquirer’s risk appetite.
Factors an acquirer may reasonably consider include:
- direction of fraud and dispute performance;
- merchant processing history;
- refund liability;
- reserve exposure;
- delivery timeframe;
- business model;
- fulfillment problems;
- card-testing activity;
- merchant cooperation;
- underwriting accuracy;
- repeated risk-program issues.
These are practical acquiring-risk factors, not a universal Visa termination checklist.
Visa’s public VAMP materials do not establish a simple rule stating that crossing one specific merchant percentage automatically requires Visa to terminate the MID. Network monitoring and the acquirer’s merchant-risk decision are distinct.
Persistent disputes create costs beyond the transaction reversal itself. The true cost of chargebacks can include operational work, dispute handling and wider pressure on the merchant’s risk profile.
How to Have the VAMP Conversation With Your Acquirer
A VAMP meeting should be a data discussion, not a defensive argument.
Bring these questions:
- What exact Visa reporting month triggered the notice?
- What VAMP numerator did you receive?
- What settled-transaction denominator did Visa use?
- How much of the numerator is TC40 fraud versus TC15 disputes?
- Is this merchant-level identification, portfolio-level remediation, enumeration, or multiple issues?
- Which channels or cohorts are responsible?
- Which pre-dispute solutions are enabled?
- What remediation milestones does the risk team require?
- Are reserve changes or contractual fees being considered?
- What performance will the acquirer require before considering the matter resolved?
A professional merchant response might read:
Thank you for the VAMP notice. We are treating the issue as a priority and have started reconciling Visa performance against our gateway, refund, fraud and fulfillment data. Please confirm the affected MID, reporting month, VAMP numerator and denominator, fraud/dispute split, applicable classification, enumeration findings and the milestones your team requires. We will provide our root-cause analysis and corrective-action results against those metrics.
Being cooperative does not mean accepting unexplained figures. Ask for enough data to reproduce the problem.
Practical Visa VAMP Prevention Checklist
Daily
- Check fraud spikes.
- Investigate sudden decline bursts.
- Watch for enumeration and card-testing patterns.
- Escalate repeated customer complaints.
- Review unusual promotional or affiliate traffic.
Weekly
- Track Visa fraud and disputes separately.
- Review refund completion times.
- Analyze top dispute categories.
- Check fulfillment delays.
- Review subscription cancellations.
- Segment fraud by channel, SKU and marketing source.
- Review pre-dispute interventions.
Monthly
- Estimate the Visa VAMP ratio.
- Reconcile settled Visa transactions.
- Review TC40 and TC15 counts.
- Check enumeration separately.
- Compare internal reporting with acquirer data.
- Review Mastercard ECP thresholds and Mastercard performance independently.
- Record fraud-control and policy changes.
- Hold a structured merchant risk monitoring review.
FAQs About Visa VAMP Thresholds
What are the current Visa VAMP thresholds?
As of October 2026, Visa’s published Excessive Merchant threshold is 150 basis points in Asia Pacific, Canada, Europe, the United States and LAC, subject to the applicable regional minimum-count conditions. CEMEA has a different published threshold and minimum condition. The AP, Canada, EU and U.S. threshold changed to 150 bps on April 1, 2026.
What does a 150-bps VAMP threshold mean?
A 150-basis-point ratio equals 1.50%. However, the percentage alone does not determine merchant identification because applicable minimum-count conditions also matter.
How is the VAMP ratio calculated?
The core calculation is qualifying Visa TC40 fraud plus qualifying TC15 disputes divided by Visa TC05 settled transactions. Eligible pre-dispute resolutions and qualifying Compelling Evidence 3.0 fraud can receive different treatment subject to Visa’s data-extract timing.
Does RDR reduce the VAMP ratio?
Qualifying disputes resolved through applicable pre-dispute solutions can be excluded under Visa’s VAMP methodology, but treatment depends on eligibility and whether the resolution occurs in time for the relevant Visa data extract. RDR should therefore be viewed as an intervention tool, not a guarantee.
Does a fraud report and dispute on the same transaction count twice?
Visa’s public VAMP fact sheet states that the numerator combines counts of TC40 fraud and TC15 disputes, but the public material does not describe every same-transaction deduplication scenario. Merchants should request the actual Visa numerator from their acquirer rather than guessing from internal transaction IDs.
What is Visa enumeration?
Enumeration is large-scale card testing designed to discover valid payment credentials. Visa monitors it separately using an enumeration ratio and enumerated authorization-attempt count that include both approved and declined authorization attempts.
How long does it take to get out of VAMP?
There is no single public merchant exit period that should be assumed for every case. Visa’s public rules refer the detailed exit process to the current VAMP Guide, so the merchant should obtain the applicable remediation and exit requirements directly from its acquirer.
Is Visa VAMP the same as Mastercard ECP?
No. VAMP combines qualifying Visa fraud and disputes and separately monitors enumeration. Mastercard ECP is Mastercard’s merchant-level excessive chargeback monitoring program. A merchant should track the two networks independently.
Can Visa VAMP get my merchant account terminated?
Yes, persistent VAMP problems can contribute to an acquirer’s decision to restrict or terminate a merchant, but crossing a threshold does not create a universal automatic Visa termination rule. The merchant’s risk profile, remediation progress and acquiring agreement also matter.
Managing Visa VAMP Thresholds Before They Become an Account Problem
The most useful way to manage Visa VAMP thresholds is to stop relying on a generic chargeback percentage.
Track Visa-specific settled transactions, qualifying fraud, qualifying disputes and enumeration separately. Reconcile those numbers with your acquirer’s network reporting, investigate differences quickly and identify whether fraud, customer-service friction, fulfillment or card testing is driving the result.
If performance is approaching the Visa VAMP thresholds, engage the acquiring bank before another reporting month closes. Effective chargeback monitoring program remediation is easier when the merchant can show the root cause, responsible owner, corrective control and measurable improvement.
The objective is not merely to get one ratio below 150 basis points. It is to build a payment operation in which excessive fraud, disputes and enumeration are detected early enough that they do not keep returning.